
In July 2024 the Customs, Excise and Service Tax Appellate Tribunal (CESTAT), Principal Bench, New Delhi, held that IC-Codecs imported by Samsung India Electronics Pvt. Ltd. are electronic integrated circuits of heading 8542, not communication apparatus of heading 8517. Customs had reclassified them under India tariff item 8517 62 90. The Tribunal restored Samsung’s classification under tariff item 8542 39 00, applying GRI 1 and the definition of electronic integrated circuits in Note 9(b) to Chapter 85, and dismissed the department’s appeal on confiscation and penalty.
The decision is Final Order No. 56037-56038/2024, pronounced on 22 July 2024 (full text of the order). It is a useful reference for anyone classifying electronic components, because it turns on the condition of the goods at the time of import and on the technical evidence each side produced.
Background
Samsung manufactures mobile phones and tablets in India. Between March 2018 and March 2019 it imported IC-Codecs (integrated circuits that work as codecs) and declared them under India tariff item 8542 39 00 as electronic integrated circuits. That classification carried basic customs duty of 7.5% and IGST of 12%, and Samsung claimed a concession under Serial No. 24 of the exemption notification dated 1 March 2005.
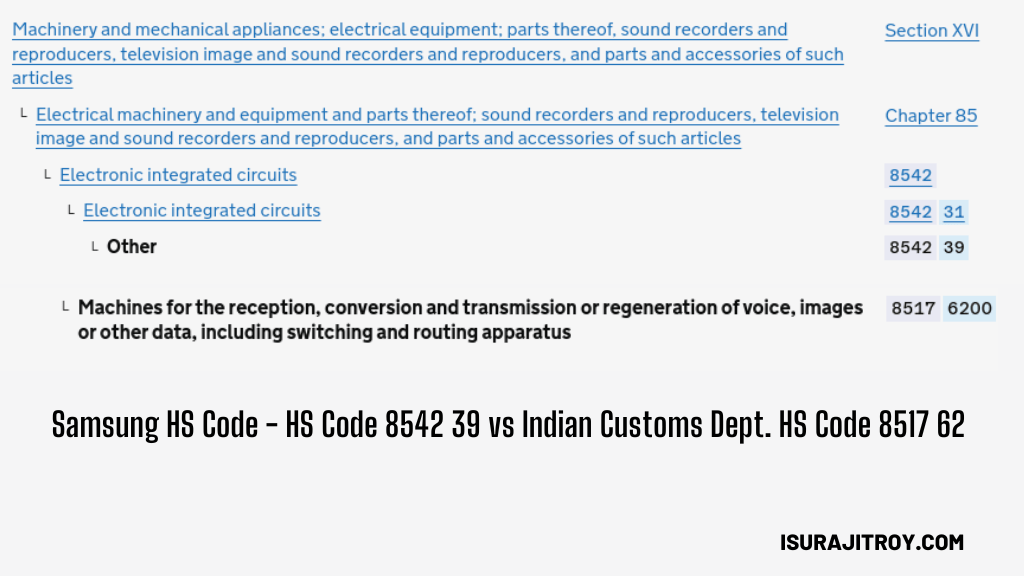
Customs reclassified the IC-Codecs under tariff item 8517 62 90 (communication apparatus), which attracted basic customs duty of 10% and IGST of 18%. The department raised a demand for differential duty of ₹1.89 crore (₹1,89,05,965), with interest. The Principal Commissioner confirmed the reclassification in an order dated 25 August 2020 but declined to confiscate the goods or impose a penalty. Samsung appealed against the classification, and the department appealed against the decision not to confiscate or penalise.
The issues before the Tribunal
1. Classification
Samsung’s case was that IC-Codecs are electronic integrated circuits under tariff item 8542 39 00, and that heading 8542 does not cover communication devices. Customs argued that they fall under 8517 62 90 as “other communication apparatus” because, once integrated with other components, they can transmit and receive data.
2. Technical features of the IC-Codecs
- The IC-Codecs are monolithic integrated circuits with digital signal processors (DSPs), general-purpose input/output (GPIO) pins and Inter-Integrated Circuit (I2C) interfaces.
- They have to be mounted on printed circuit boards (PCBs) and given an external power supply before they work. As imported, they cannot transmit or receive data on their own.
3. Which rules apply

- The department relied on Notes 2(b), 3 and 4 to Section XVI and argued that components used in mobile phones must be classified as parts of communication apparatus.
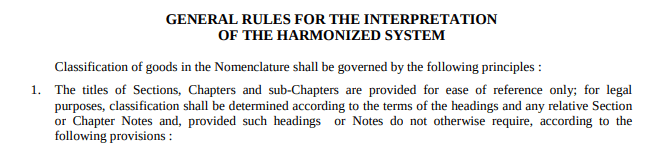
- Samsung relied on Rule 1 of the General Rules for Interpretation and argued that the goods must be classified on their characteristics at the time of import.
4. Revenue neutrality
- Samsung also argued that even if the goods fell under heading 8517, the IGST paid on import would be available as credit, so the demand was revenue-neutral.
The Tribunal’s findings
- The IC-Codecs, as imported, are electronic integrated circuits. They do not have, in the Tribunal’s words, “the capability of transmission of data at the time of import”, so they are not communication apparatus. Under GRI 1, heading 8517 covers apparatus and machines, and the imported chips did not answer to any description in it.
- Heading 8542 covers electronic integrated circuits, including monolithic integrated circuits such as these. The Tribunal applied the definition in Note 9(b) to Chapter 85 and the HSN Explanatory Notes, which state that monolithic integrated circuits may be in the form of un-diced wafers. It recorded that the IC-Codecs were imported in rolls, as un-diced wafers, and upheld Samsung’s classification under 8542 39 00.
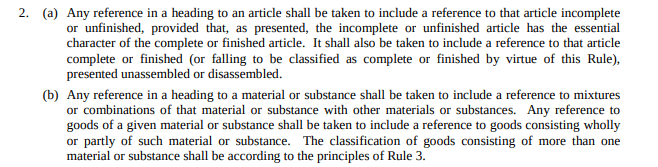
- The department had produced no technical literature to support classification under heading 8517. The Tribunal also held that Rule 2(b) of the GRIs had no relevance, as the product “is not a mixture or combination of materials or substances”.
- Samsung was entitled to the benefit of the exemption notification dated 1 March 2005. Having decided the classification, the Tribunal found it unnecessary to examine the remaining contentions, so it did not rule on revenue neutrality.
- The department’s appeal against the refusal to confiscate the goods under Section 111(m) and to impose a penalty under Section 112(a)(ii) of the Customs Act failed because, as the Tribunal put it, the order on merits could not be sustained.
Final order
The Tribunal disposed of both appeals together:
1. Customs Appeal No. 51172 of 2020, filed by Samsung, was allowed. The classification under 8517 62 90 was set aside and the IC-Codecs were held classifiable under heading 8542 (tariff item 8542 39 00).
2. Customs Appeal No. 51204 of 2020, filed by the department against the Principal Commissioner’s decision not to confiscate the goods or impose penalties, was dismissed.
Analysis and implications
- A component is classified in the condition in which it is imported. The Tribunal looked at what the IC-Codecs could do at the border, not at what the finished phone does. The same principle runs through the case study on GRI 2(a) and the “as presented” doctrine.
- Technical evidence decided the appeal. Samsung’s documents showed the goods were integrated circuits, and the department had no technical literature in reply. A classification file that records the technical basis for each code, as described in building an audit-proof HS classification file, is the first line of defence in a dispute like this.
- Samsung argued revenue neutrality, but the Tribunal did not rule on it. The appeal was won on classification alone.
- Advanced electronic components remain hard to classify, because the same chip can be described by what it is or by what the finished product does. Clear tariff texts and Explanatory Notes reduce the room for this kind of dispute.
- For manufacturers that depend on imported components, a decision like this limits reclassifications that raise duty costs without a technical basis.
What the decision settles
The point of the Samsung decision is narrow and practical. An IC-Codec that cannot transmit or receive data until it is mounted on a board and powered is an integrated circuit of heading 8542, whatever the finished phone does. The department lost because it reclassified the goods by their end use and had no technical evidence to show that the chips, as imported, were communication apparatus.
For more on how Explanatory Notes are used in disputes of this kind, see the role of Explanatory Notes in resolving classification disputes. A later CESTAT decision on multimedia speaker systems takes the opposite approach: there the Tribunal classified a whole audio system by the function of its main unit.