
Global trade is the exchange of goods and services across national borders. In practice it runs as a chain: a seller in one country exports, a buyer in another imports, carriers move the goods, banks move the money and insurers cover the risks, and at each border the government applies its own rules on duties, licences and documents.
What global trade covers
Countries trade because demand differs from one country to another and because resources and production capacity are spread unevenly. A country with large mineral deposits but little manufacturing will sell ore and buy machinery; a country with the opposite profile does the reverse. The economic reasons behind this pattern are covered in our article on the main theories of international trade.
Trade is more than physical goods crossing a port. It also includes services, intangible assets such as patents and software licences, cross-border investment and work subcontracted to companies abroad.
Who takes part
Three groups drive global trade: governments that set the rules, businesses that make and sell the goods, and consumers who buy them.
Governments
Governments write trade policy and negotiate agreements with other countries. They also enforce the rules at the border: they set and collect tariffs, impose embargoes and use diplomacy to protect their own economic interests.
Businesses
Companies do most of the actual trading. They make goods and sell services in several countries to reach more customers, to use suppliers abroad, and to take advantage of lower costs or particular skills in other countries.
Consumers
Consumers are at the end of the chain. Imports give them access to goods from other parts of the world, and foreign competition tends to push prices down and quality up while widening the choice on the shelf.
How a cross-border transaction works
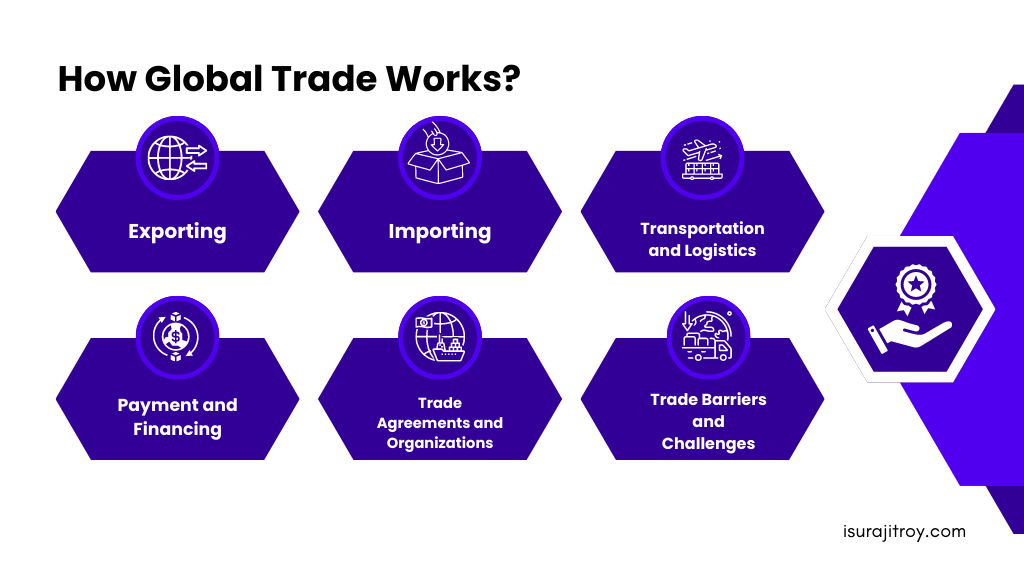
Every international sale involves the same basic steps, whatever the product.
Exporting
Exporting is selling goods or services made in one country to a buyer in another. The exporter has to follow its own country’s export rules. That means obtaining any licences or permits the goods need and preparing the shipping documents, usually a commercial invoice, a packing list and, where required, a certificate of origin.
Importing
Importing is buying goods or services produced abroad and bringing them into your own country. The importer pays customs duties, taxes and fees, and meets any import licensing requirements. Customs identifies goods by their tariff classification code, which is built on the international Harmonized System (HS). The code sets the duty rate and is often what triggers licensing and other import requirements. Our article on the legal basis of HS classification explains how that code is determined.
Transport and logistics
Goods move by sea, air, road or rail. Logistics also covers warehousing, inventory control and customs clearance at both ends of the journey.
Payment
Money has to move from a buyer in one country to a seller in another, usually in a different currency. The usual methods are letters of credit, bank transfers and other trade finance instruments, combined with currency exchange and some form of protection against non-payment. These are covered in the trade finance section below.
Trade agreements and organisations
International rules shape how all of this works. The World Trade Organization (WTO) is the organisation that administers the multilateral trading rules. Alongside it are regional trade agreements, such as the United States-Mexico-Canada Agreement (USMCA), and bilateral agreements between two countries. These agreements set norms and standards for cross-border trade and can lower tariffs for goods that qualify.
Trade finance and insurance
Exporters want to be paid before they lose control of the goods; importers want the goods before they pay. Trade finance bridges that gap. Letters of credit, export credit and trade finance loans reduce payment risk and give both sides working capital while goods are in transit.
Trade insurance covers what can go wrong along the way: the buyer failing to pay, political events in the buyer’s country, and loss or damage during transport. Our separate article on trade finance explains these instruments in more detail.
Global supply chains
A global supply chain is a production and delivery system that crosses several countries. Raw materials, components, services and data pass from material suppliers to manufacturers, then to distributors and retailers, often in different countries at each stage.
Spreading production this way gives companies access to resources, labour and markets they would not have at home. It also exposes them to disruption, delays and other risks at every border the goods cross. One of those risks is that each country applies its own duty rates and national codes to the same product, which we look at in how country-specific tariff variations affect your supply chain.
Effects of global trade
Trade affects national economies, companies and communities in different ways.
Economic growth
Trade enlarges markets, increases competition and encourages countries and companies to specialise in what they produce most efficiently. It can create jobs, generate tax revenue for governments, and spread innovation and technology from one country to another.
Business opportunities
For companies, trade opens new markets and a larger customer base. It also lets them buy raw materials and components from other countries and gain access to technology and specialist knowledge they could not find at home.
International relations
Trade ties countries together economically and diplomatically and encourages cultural exchange. Trade negotiations and agreements are also one of the ways countries settle disputes with each other.
Sustainable development
Sustainable development means meeting present needs without compromising the ability of future generations to meet theirs. Trade can support it when companies follow responsible business practices, protect the environment and treat workers fairly. Fair trade practices and responsible supply chain management can contribute to the United Nations’ Sustainable Development Goals (SDGs), which include reducing poverty and inequality and tackling climate change.
Challenges and disputes
Trade brings benefits, but it also creates friction between countries and costs for the businesses involved.
Trade barriers
Tariffs, quotas and non-tariff barriers slow the movement of goods across borders and can give some producers an unfair advantage. Tariffs in particular often lead to disputes between countries. Our article on tariffs and trade barriers explains the main types and their effects.
Geopolitical tensions
Trade disputes, sanctions and political conflict between countries make trade less predictable. They can interrupt supply chains, change where companies produce, and unsettle trade more generally.
Environmental and social concerns
Trade has been linked to deforestation, pollution, labour exploitation and human rights abuses. These concerns have led to closer scrutiny and more regulation of international trade, with more attention to sustainability, responsible sourcing and corporate social responsibility.
Currency fluctuations
Changes in exchange rates alter the price of goods and services between countries. A sudden move can wipe out the margin on a contract priced in another currency, which makes currency risk one of the everyday risks of trading across borders.
Intellectual property rights
Patents, trademarks and copyrights protect a company’s products, inventions and brand. Infringement across borders is a common source of legal disputes in international trade.
New technologies
E-commerce, blockchain and automation are changing how trade is done and can make it faster, more transparent and more secure. They also raise problems of their own, including data privacy, cybersecurity and the loss of jobs to automation. Companies have to adapt to these technologies to stay competitive and compliant.
Trade agreements and policy changes
Trade agreements, free trade agreements (FTAs) and customs regulations set the terms on which companies trade: the tariffs they pay, any quotas, the conditions for entering a market and the regulatory obligations they must meet. When these agreements and policies change, or when the political balance between countries shifts, businesses face new uncertainty.